Just a month ago, everyone was asking whether to stop their SIP. Now the question has flipped: “The market is flying. Should I put more money in right now?”
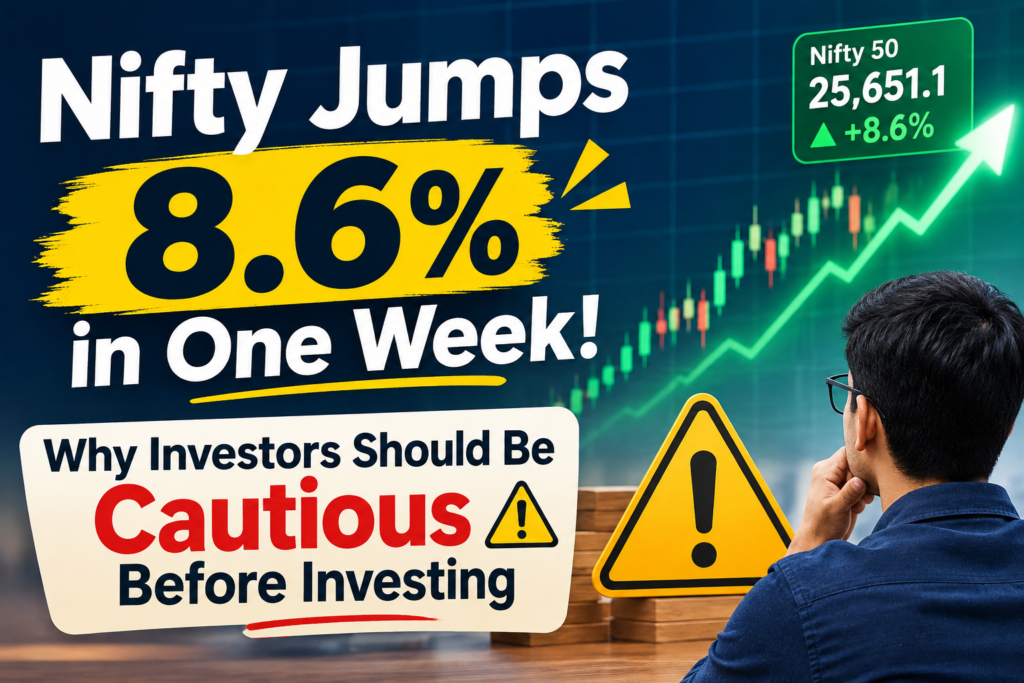
In the week from 2 to 6 November 2026, the Nifty 50 rose 8.58% to close at 25,030, its biggest weekly gain since early 2021. The Sensex rose 8.82% to about 81,028. Foreign investors, who had been selling Indian shares for most of the year, bought about ₹45,960 crore in a single week. Lower crude oil prices and a stronger rupee added fuel.
That is good news for anyone who stayed invested. But a sharp rally is also exactly when investors make some of their most expensive mistakes. Here’s why it pays to be cautious, and what cautious actually looks like.
What happened last week, in short
- Nifty 50: up 8.58% for the week, closing at 25,030 (up about 1,977 points)
- Sensex: up 8.82%, closing at about 81,028
- Midcaps and smallcaps: up less. The Nifty Midcap 150 rose 5.84% and the Nifty Smallcap 250 rose 3.72%
- Since the 8 October low (near 22,180): the Nifty has bounced about 13%, but is still below its January high
- What drove it: heavy foreign buying, a fall in crude oil prices, a stronger rupee and easing tension in West Asia
1. One great week is not a trend
An 8.6% jump in five days is unusual. Big moves like this often come after a long fall, when prices have become cheap and sellers run out. But the road after such a bounce is rarely a straight line. Markets can go sideways or give back part of the gain while they wait for the next piece of news.
The worries that pushed the market down this year have eased, but they haven’t disappeared: global interest rates, crude oil, the rupee and geopolitics can all turn again. Invest because your plan says so, not because of one week’s headline.
2. Money that comes in fast can leave fast
A large part of last week’s rally came from foreign investors returning. That is welcome, but the same investors sold more than ₹2.5 lakh crore of Indian shares earlier this year. Their money moves with global events, and it can reverse quickly. A rally built mostly on fast-moving money deserves some respect.
3. Fear of missing out is the most expensive feeling in investing
When markets fall, people stop investing. When they rise sharply, the same people rush back in, often with a large lump sum, at higher prices. This is how many investors end up buying high and selling low without meaning to.
If you paused your SIP during the fall, this is a good time to restart it. But restarting your SIP is very different from putting all your savings in at once because you’re afraid of missing the next week.
4. Don’t chase last week’s winners
The big gains came mostly from large companies and a few sectors. Switching your funds into whatever rose most last week usually means buying them after the jump. Choose funds for your goal and time horizon, not for their last five days.
What being cautious looks like (it doesn’t mean staying out)
Being cautious does not mean waiting on the sidelines for the “perfect time”. Nobody knows if the market will be higher or lower in three months. It means investing in a way that doesn’t depend on guessing right.
- Keep your SIP running. Don’t stop it and don’t suddenly double it. A SIP already spreads your buying across good months and bad ones.
- Spread out a lump sum. If you have a bonus or savings to invest, consider an STP (Systematic Transfer Plan): park the money in a liquid or low-risk fund and move a fixed amount into equity every month for 6 to 12 months.
- Check your asset allocation. After a big rally, your equity share may be higher than you planned. If it is, bringing it back to your target is sensible.
- Keep your safety net separate. Your emergency fund and money for goals within 2 to 3 years should not go into equity, however good the market looks.
- Talk before you act. A 15-minute review can stop a decision made in excitement.
A simple example: lump sum vs spreading it out
Say you have ₹6 lakh to invest in an equity fund whose NAV is ₹100 today. You can invest it all at once, or move ₹1 lakh a month over 6 months through an STP. Here’s what happens in two different futures:
| Market dips first, then recovers to ₹100 | Market keeps rising to ₹110 | |
|---|---|---|
| NAV over the 6 months | 100, 94, 90, 88, 92, 96, then 100 | 100, 102, 104, 106, 108, then 110 |
| All ₹6 lakh at once | ₹6,00,000 | ₹6,60,000 |
| ₹1 lakh a month (STP) | ₹6,43,993 | ₹6,29,238 |
Neither approach wins every time. If the market keeps rising, investing at once does better. If it dips first, spreading it out does better. Because nobody knows which future we’ll get, spreading it out reduces the chance of a painful regret, and that is the whole point of being cautious.
This is an illustration with assumed NAVs, not a real fund. It ignores the returns on money waiting in the liquid fund, taxes and exit loads. Actual results will differ.
The bottom line
Last week’s rally is a reminder of why staying invested matters: the investors who kept their SIPs going through the fall are the ones enjoying the bounce. But a sharp rise is not a signal to throw caution away. Be cautious, not fearful: keep your SIP going, spread out any big amount, and stick to your plan.
Thinking of investing a lump sum after this rally? Book a free 15-minute call with EquityEdge Investments, or message us on WhatsApp. We’ll look at your goals and suggest a sensible way to invest it, no pressure.
Frequently asked questions
Is it a good time to invest after the market has rallied? Nobody can say where the market will go next. For long-term goals, regular investing through a SIP matters more than timing. For a lump sum, spreading it out over a few months reduces the risk of investing just before a dip.
Should I stop my SIP because the market is high? No. A SIP is designed to keep going through highs and lows. When prices are higher it buys fewer units, and when they fall it buys more.
What is an STP? A Systematic Transfer Plan moves a fixed amount from one fund (usually a liquid or low-risk fund) to another fund, often equity, at regular intervals. It is a common way to invest a lump sum gradually.
I paused my SIP during the fall. Should I restart now? Yes, if your goals and budget haven’t changed. Restart at your usual amount rather than trying to make up the missed months all at once.